Home Buying

Your Complete Guide to Buying a Home in Charlotte, NC

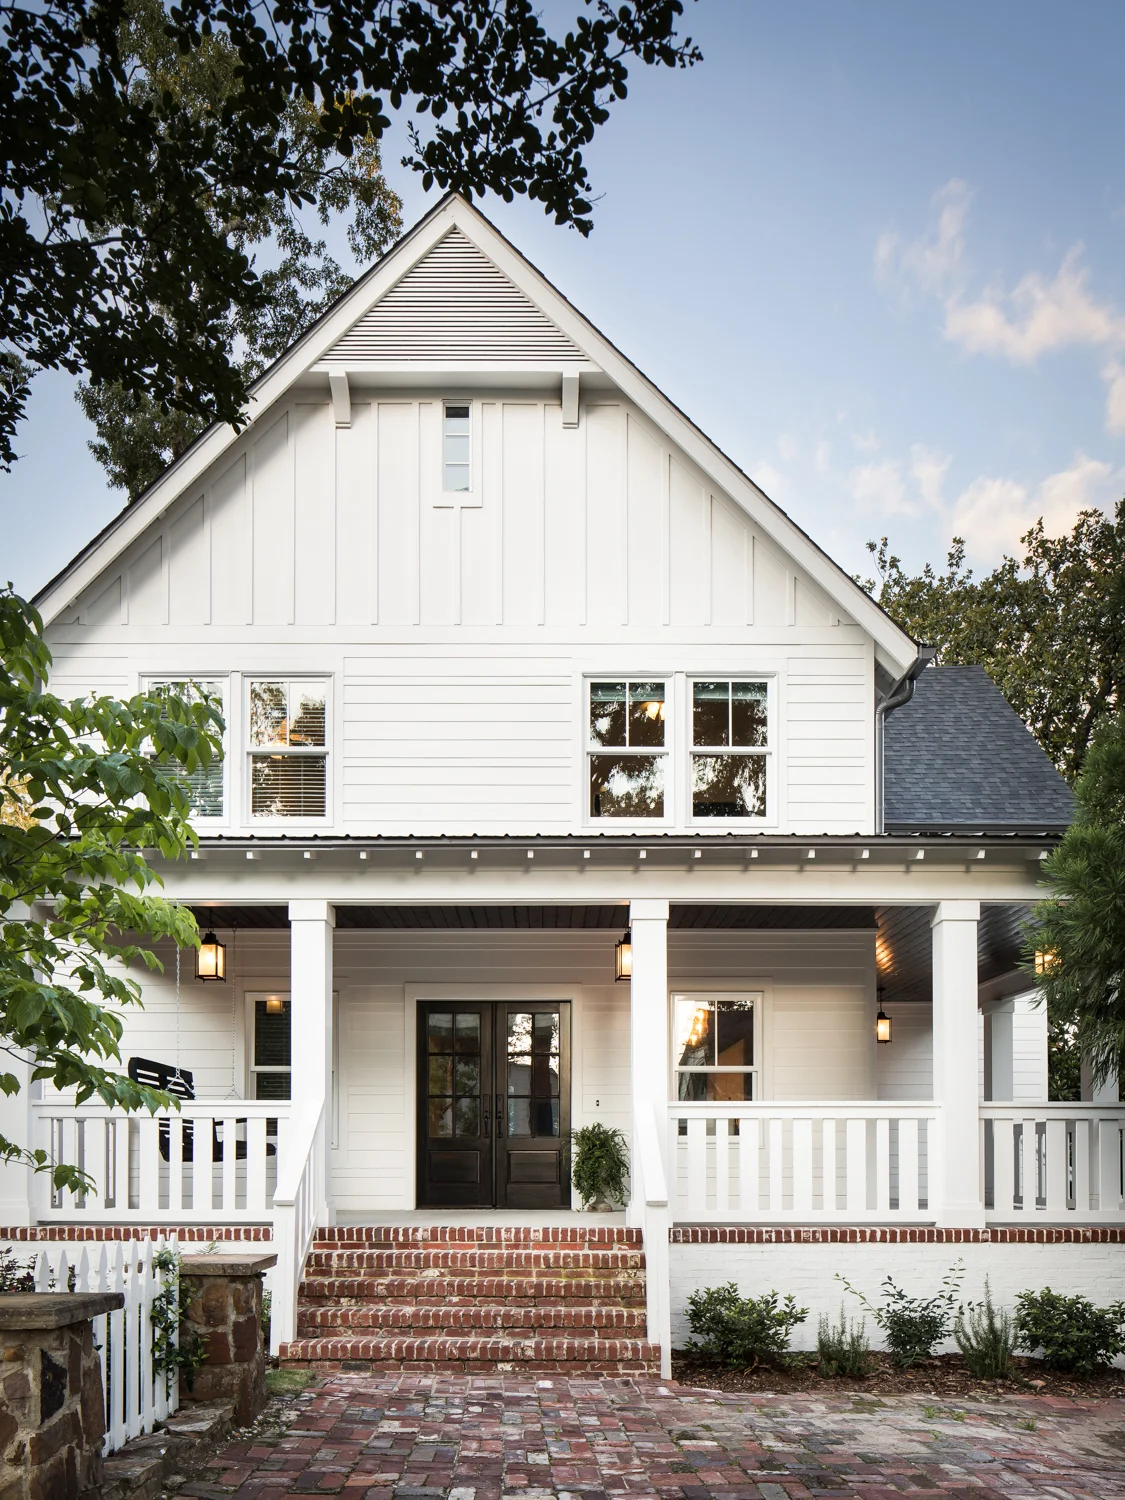
White painted cottage style home in Charlotte
Every step from pre-approval to closing day, in plain language.

Buying a home is one of the most exciting decisions you will ever make. It is also one of the most complex. Between financing, negotiations, inspections, and closing, there are a lot of moving parts, and the decisions you make today will have real financial consequences for years.

The good news is that with the right preparation and the right agent in your corner, the process does not have to be overwhelming.

Whether you are a first-time buyer, relocating to Charlotte from out of town, or coming back to the market after a few years away, this guide is designed to give you a clear, honest walkthrough of what it actually takes to buy a home in Charlotte, NC, and how to do it with confidence.

01. What to Know Before Buying a Home in Charlotte, NC

Before you start touring homes, take an honest look at your financial picture. These are the six areas every buyer should think through before jumping in.

  1. Credit Score. A score of 620 is typically required for conventional loans, while FHA loans have more flexibility depending on your down payment. The higher your score, the better your rate.
  2. Job and Income. Do you have a stable job and income? Are you staying in this line of work? Lenders want to see consistency.
  3. Down Payment. Depending on the loan type, your down payment can range from 0% to 20% of the purchase price. Knowing your number early helps set your budget.
  4. Ongoing Costs. As a homeowner, your budget should account for monthly mortgage payments, property taxes, homeowners insurance, and maintenance costs. Maintenance costs typically run 1% to 2% of the purchase price per year.
  5. Closing Costs. Closing costs range from 2% to 6% of the loan amount and include inspection and appraisal fees. Factor these in before you fall in love with a price point. My guide to North Carolina closing costs for buyers breaks down each line.
  6. Long-Term Planning. Do you plan to stay in this area? Consider how your career, family, and lifestyle might evolve over the next several years before committing to a location. If you are still narrowing down where to focus your search, my Charlotte neighborhood guides break down the seven areas I know best.

02. Choose Your Agent

Choosing the agent you work with to buy your home is a big decision. Your agent should:

  • Understand your goals and the local market
  • Have a track record of working hard on behalf of their clients
  • Be focused on protecting your interests, not just on closing a deal

The value of a buyer's agent

A great buyer's agent brings far more to the table than just opening doors. With me, you get:

  • Exclusive representation with your interests at the center
  • Access to a network of trustworthy lenders
  • Advice based on current market conditions in your target neighborhoods
  • Tight management of transaction deadlines so nothing slips through the cracks
  • Access to off-market and "coming soon" listings
  • Terms negotiated in your favor, not the seller's
  • Help identifying property potential and red flags before you overpay
  • Recommendations for trusted service providers
  • Protection from overpaying in a competitive market
  • Help decoding legal jargon and contract language
  • Professional management of your offer submission
  • A focus on making closing day smooth, not stressful

Questions to ask before you hire an agent

  1. What is your experience helping clients like me?
  2. Do you specialize in any particular neighborhoods or property types?
  3. How do you help buyers compete in this market?
  4. What is your role in the negotiation process?
  5. What is your preferred communication style?
  6. What is your fee structure or compensation requirements?
  7. What sets you apart from other agents?

My focus: seven neighborhoods I know in depth


03. Understand Your Debt-to-Income Ratio

Your debt-to-income (DTI) ratio measures your monthly debt payments against your gross monthly income. It helps you assess your financial health and your ability to take on a mortgage.

Why it matters: mortgage lenders have specific DTI requirements and generally prefer borrowers to have a DTI below 43%, including the new mortgage payment.

What the numbers mean

  • Under 36%: you are in great shape.
  • 37% to 43%: there is room for improvement.
  • Above 45%: this may pose challenges. Speak to a lender for guidance on qualifying.

Interactive tool

Calculate your debt-to-income ratio

04. Get Pre-Approved for a Mortgage

The next step is to understand how much you qualify for by meeting with a local lender and getting a pre-approval letter. It is important to speak with a few lenders to find the right fit. Keep in mind that a pre-approval is typically valid for only 30 to 90 days, so secure that letter closer to when you are ready to actively make offers.

Questions to ask your lender

  1. What type of loan do you recommend for me and why?
  2. Do I qualify for any down payment assistance programs?
  3. What is the interest rate, and what is the APR?
  4. Will I pay mortgage insurance?
  5. What will my estimated monthly payment be?
  6. Can I lock in an interest rate? For how long and at what cost?
  7. What will my closing costs be?
  8. Is there anything else I should know?

See my complete guide to Charlotte down payment assistance

Trusted lender partners

These are lenders I have worked with and trust. I receive no compensation for referrals, per RESPA.


05. Define Your Needs vs. Wants

Before we jump into the home search, separate what you must have from what would be nice to have. This keeps us focused on the right homes and prevents you from compromising on the things that matter most.

Needs are the non-negotiables:

  • Enough bedrooms for your family
  • Proximity to work or school
  • An attached garage, if you need one. These are the items you cannot easily change after the fact.

Wants are the nice-to-haves you can live without or add down the road:

  • A specific paint color
  • A fenced yard
  • Particular flooring
  • A walk-in shower

Remember: you can change almost anything inside a home. You cannot change the lot, the location, or the price you paid. This is why understanding the neighborhood you are buying into matters more than almost any other decision in this process.

Home search worksheet

  1. What area or areas of Charlotte are you interested in, and what do you like about them? Not sure yet? Start with my Charlotte neighborhood guides for a side-by-side look at the seven I know best.
  2. How many bedrooms, bathrooms, and square feet do you need?
  3. Do you have children or pets? Do you work from home?
  4. What is your favorite home style?
  5. What are the five most important things in your future home?
  6. Is there a non-negotiable feature you absolutely must have?
  7. Do you prefer move-in ready or a home you can renovate?

06. Touring Homes

My best showing tips

  1. Review your Needs vs. Wants list before each showing. Keeping it fresh helps you stay objective.
  2. Use Google Street View ahead of time to get a feel for the neighborhood before you arrive.
  3. Take photos and videos at every home. Your memory will blur after a few showings.
  4. Pay close attention to the lot, lot size, and location. These cannot be changed.
  5. Look past staging and decor. Those things leave with the seller.
  6. Do an after-dark drive-by. The feel of a neighborhood can change significantly at night.

What to look for beyond the surface

  • Structural integrity: look for signs of water damage, cracks in walls or ceilings, and sloping floors.
  • Noise levels: consider proximity to roads, businesses, airports, and railways.
  • Roof and water damage: check for leaks near plumbing sources, water stains on ceilings, or damage to siding, windows, and doors.
  • Layout and flow: does the home's layout suit your daily routine? Check room sizes, storage, and how rooms connect.

07. Writing Your Offer

So you found the one. Here is how we make the offer count.

We will include your pre-approval letter to show the seller you are serious, qualified, and ready to purchase. We will also gather information about what the seller is looking for. Understanding their motivations gives us a meaningful edge when crafting the offer.

In a competitive market, you may only get one shot, so we put our best foot forward from the start. We will use comparable sales and current trends as our guide, and where it makes sense, we will propose a faster closing timeline to signal that we are ready to move.

Understanding the key terms in your offer

  1. Purchase Price. The amount you are offering to pay. It is negotiable based on market conditions, comparable sales, and the condition of the home.
  2. Due Diligence and Earnest Money. In North Carolina, due diligence money is a non-refundable fee paid to the seller for taking the home off the market during inspections. Earnest money is a refundable deposit held in escrow to show serious intent to buy. If the sale closes, both are credited to the buyer.
  3. Due Diligence Period. A negotiated window where you can inspect the property, secure financing, and conduct evaluations. You can back out for any reason during this period, but the due diligence fee is non-refundable. Once the period ends, backing out risks losing your earnest money.
  4. Contingencies. In many states, a contingency is a condition that must be met before a purchase can be finalized. The standard North Carolina contract works differently, and the due diligence period does that job instead:
    • There is no loan or appraisal contingency in the standard contract. If your loan or the appraisal falls short, your protection is the right to terminate during the due diligence period, so timing matters. I cover the options in my guide to low appraisals in North Carolina.
    • There is no separate inspection contingency either. During the due diligence period you can inspect, then renegotiate, accept the property as it is, or terminate for any reason.
  5. Closing Costs. These include lender fees, title insurance, taxes, and other costs associated with finalizing the sale, typically 2% to 5% of the purchase price.
  6. Closing Date. The date you and the seller agree to finalize the transaction and transfer ownership, usually 30 to 45 days from offer acceptance.

08. Due Diligence and Inspections

Even if a home looks perfect, inspections are critical. A home inspection uncovers hidden issues like leaks, faulty wiring, and foundation problems that are not visible to the naked eye. Skipping this step could mean expensive surprises after you move in. Keep in mind that in North Carolina a general home inspection does not cover termites or radon, which are separate reports, and I explain each in my guide to home inspections, radon, and termite reports.

In North Carolina, the due diligence period typically lasts 14 to 21 days. Schedule all inspections immediately after signing the contract to give yourself enough time to negotiate repairs or credits before the period ends.

If inspections reveal problems, you have options:

  • Request the seller make repairs
  • Ask for a credit at closing
  • Negotiate a price reduction
  • Back out entirely during the due diligence period

The due diligence fee is non-refundable regardless of outcome.

Once you are under contract, start shopping for homeowners insurance right away. Lenders require proof of coverage before approving your mortgage, so getting multiple quotes early in the process puts you ahead.

Insurance types and estimated costs

09. You Are Under Contract

Here is what happens between signing the contract and getting your keys.

Interactive checklist

Tap each step to see what it involves


10. Closing Day: What to Expect

  1. Loan Approval. After the appraisal and inspection, your lender will finalize your loan. You will hear the words "clear to close."
  2. Review Your Closing Disclosure. At least three days before closing, your lender sends a closing disclosure outlining the final interest rate, loan amount, and total closing costs. Review it carefully. This document tells you exactly how much to bring on closing day.
  3. Arrange Utilities Transfer. Contact utility providers to set up electricity, gas, water, and internet for your closing or move-in date.
  4. Obtain Certified Funds. Bring a cashier's check or wire transfer for your down payment and closing costs. Personal checks are not accepted. Your closing agent will give you the exact amount a few days before closing.

What makes up your cash to close:

Interactive tool

Estimate your total cash to close


Client spotlight

Caitlin and Berry, relocating from California, were first-time buyers in a competitive Charlotte market, buying entirely through virtual showings.

As their on-the-ground representative, I:

  • Toured homes via FaceTime
  • Provided clear, unbiased feedback on each property
  • Kept the process moving smoothly despite the time zone difference and distance
  • Stayed focused on long-term fit rather than rushing a deal

The result was that they purchased with confidence, felt genuinely represented rather than sold to, and had a smooth experience from first showing to closing day.

"We had an awesome experience working with Dante as first-time home buyers. He was patient and a strong advocate throughout the process. When looking at homes, I always felt like he had our best interests in mind over trying to close a deal. When we had questions, he was responsive outside of normal work hours and organized in making sure all steps were completed in a timely manner."

Caitlin and Berry

What other clients are saying


Want this as a step-by-step system, not just an article?

I turn this guide into a full first-time and relocating buyer onboarding for the people I work with:

  • A downloadable PDF version with checklists
  • Optional video walkthrough where I walk through each step
  • A short 15-minute clarity call to map out your exact situation
  • A neighborhood shortlist based on your budget and lifestyle

If you are thinking about buying a home in Charlotte and want to talk through where you stand, reach out below and let's have a conversation.

Dante Pinto, Charlotte REALTOR®
Dante Pinto
REALTOR® · The Redbud Group at KW SouthPark

Dante Pinto is a Charlotte REALTOR® specializing in the central Charlotte neighborhoods and serving buyers and sellers across the greater Charlotte area and the full Canopy MLS. NC Real Estate Broker #349833, The Redbud Group (Firm #C12658) at Keller Williams SouthPark, BIC Brijal Shah.